Deutschland
M&A Wave: Why Operators Are Buying Each Other Up
Trends in the M&A wave for operators
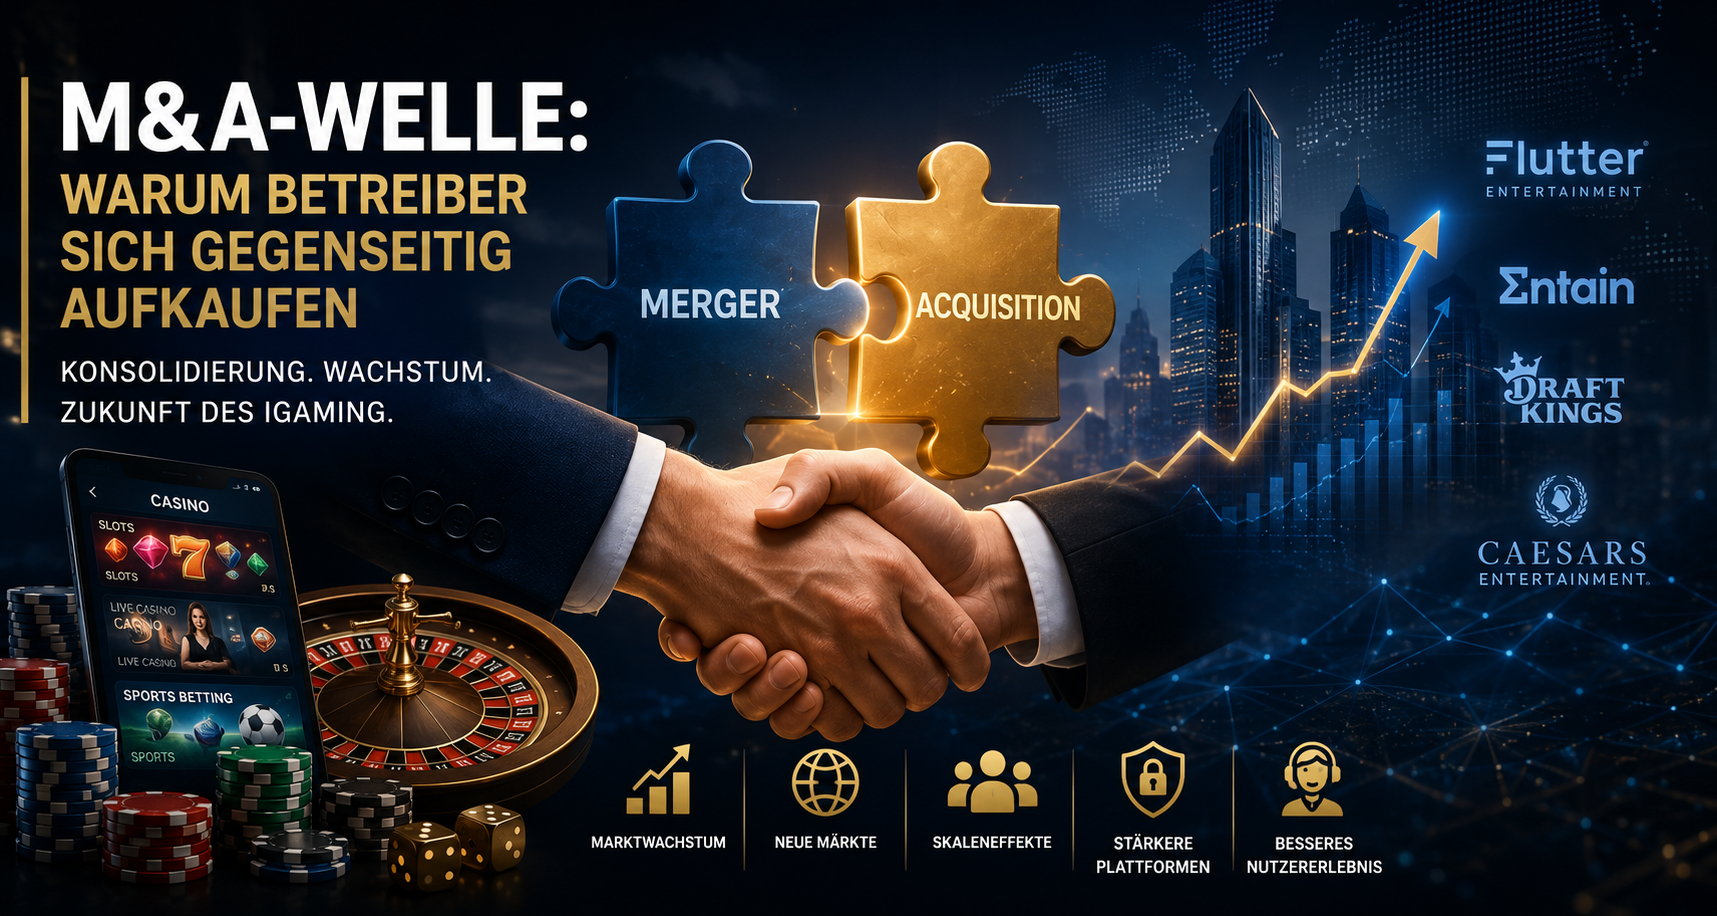
The gambling market has changed dramatically in recent years. Mergers and acquisitions (M&A) are shaping the industry like never before. Large corporations are swallowing up smaller providers, while once-independent operators become brands within vast portfolios. This development doesn't just affect investors and shareholders; it also changes the offering that players encounter every day.
What the term M&A means in iGaming
Mergers and acquisitions describe two different processes. In a merger, two companies join together to form a new entity. In an acquisition, one company buys another and absorbs it. Both forms are common in the gambling industry, though acquisitions occur far more frequently due to rapid market consolidation. In practice, however, the lines between the two models often blur, as many deals are announced as mergers of equals but effectively amount to acquisitions.
Some of the industry's biggest names have emerged through such deals. The 2016 merger of Paddy Power and Betfair to form Flutter Entertainment is regarded as a milestone. The acquisition of William Hill by Caesars Entertainment in 2021 for around £2.9 billion also demonstrates the enormous sums involved. Entain, formerly GVC Holdings, likewise grew into one of Europe's largest operators through a series of strategic acquisitions. These groups now manage dozens of brands in parallel, serving very different target audiences across various countries.
The driving forces behind consolidation
The reasons behind operators' appetite for acquisitions are complex. Regulatory pressure, rising costs and the desire for market share all play a part. Smaller providers come under pressure because they can barely keep up with the compliance requirements and marketing budgets of the larger players. For established groups, meanwhile, acquisitions are often quicker and cheaper than organic growth.
Several factors combine to accelerate the current wave:
● Regulation: New licensing requirements, such as the German Interstate Treaty on Gambling of 2021, significantly increase operating costs.
● Technology: Access to powerful platforms and data analytics is expensive and easier to secure through acquisitions.
● Market access: Deals open the door to new countries with existing licences and customer bases.
● Economies of scale: Larger companies negotiate better terms with game developers and payment providers.
● Diversification: Operators combine sports betting, casino and online poker under one roof.
How acquisitions affect the games on offer
For users, the consequences of M&A activity are often mixed. On the one hand, they benefit from larger game libraries and more stable platforms, as financially strong groups invest more in security and choice. On the other hand, consolidation can limit variety when independent brands disappear or become standardised. A broad offering nevertheless remains a key selling point, as shown by the portfolio at https://nv.casino/de, which ranges from slot machines to live formats.
Classic table games in particular benefit from larger operator structures, as these can fund high-quality live dealer studios. Anyone specifically looking for https://nv.casino/de/category/baccarat will usually find a wider range of variants and stake limits within consolidated portfolios. This concentration of resources raises technical quality but can reduce the number of independent niche providers.
Facts and figures on the current market situation
The financial scale of the industry illustrates why M&A deals are so attractive. The global online gambling market was estimated at over 90 billion US dollars in 2024, with growth rates remaining in double digits. Analysts expect the market volume could nearly double by the end of the decade. In such an environment, companies secure strategic positions through acquisitions.
| Year | Transaction | Approximate value |
|---|---|---|
| 2016 | Paddy Power and Betfair (merger) | approx. £5 billion |
| 2020 | Caesars acquires William Hill | approx. £2.9 billion |
| 2022 | DraftKings acquires Golden Nugget Online | approx. $1.56 billion |
| 2023 | 888 integrates William Hill International | approx. £2.2 billion |
Risks and limits of the acquisition strategy
As tempting as acquisitions may appear, they carry considerable risks. Integrating different corporate cultures, IT systems and licensing structures fails more often than the headlines suggest. In addition, competition authorities are scrutinising large deals ever more closely to prevent monopolies from forming. Excessive debt from costly acquisitions can burden operators in the long term if expected synergies fail to materialise. It's not uncommon for groups to have to divest entire business units shortly after an acquisition because the original expectations weren't met.
Regulatory intervention has increased in recent years. In Germany and other European markets, advertising restrictions and player protection requirements are taking centre stage. These conditions influence which deals are approved at all and how profitable they ultimately turn out to be. Authorities can impose conditions, such as requiring the sale of certain brands, before approving a merger. Such conditions prolong negotiations and significantly increase uncertainty for all parties involved.
A look at the next phase of the market
Consolidation is likely to continue, albeit under different conditions. Rather than sheer size, specialised capabilities are moving into focus, for instance in artificial intelligence, personalised offerings and responsible gambling. Operators are increasingly seeking technology partners whose expertise would be difficult to build up themselves.
Several trends are emerging for the coming years:
More acquisitions of technology and data companies rather than pure operators.
Stricter regulation, making cross-border deals more complex.
The growing importance of niche markets, where smaller providers can survive.
Higher demands for transparency and player protection following every merger.
What players can take away from the M&A wave
The wave of acquisitions is permanently changing the face of the gambling industry. For users, it often means more choice, better technology and more stable platforms, but also fewer independent brands. Anyone who understands the background to these deals can
Max Schmidt
Lokaler Experte